409A valuation
409A appraisalA 409A valuation is an independent appraisal of what one share of a private company's common stock is worth. The tax regulations presume an independent appraisal reasonable for up to 12 months, unless later information materially affects the value. A stock option granted with a strike below it falls under Section 409A.
What is a 409A valuation?
The name comes from Section 409A of the US tax code, which adds a 20% federal penalty tax, on top of income tax, when stock options are granted below fair market value. A public company reads that value off the market. A private company has no market, so it hires an outside appraiser, and the appraiser's per-share figure is the 409A.
A 409A values common stock, the class employees hold. Investors buy preferred stock, which carries rights common stock does not, so the 409A and the price in the latest funding round are different figures.
A valuation is presumed reasonable for up to 12 months. Information that materially affects the company's value ends that presumption sooner. Over a few years a company accumulates a history of them, and that history is the only price record its common stock has.
How a 409A valuation works, with numbers
A company's 409A comes in at $4.20 a share, so options granted that month carry a $4.20 strike. A year later the next 409A says $6.80.
On 10,000 vested options from the first grant, the spread is $2.60 a share, or $26,000. That is a figure on paper, before tax, for shares that may not be sellable.
- New 409A, per share
- $6.80
- Strike, per share
- − $4.20
- Vested options
- × 10,000
- Spread
- $26,000
Why a 409A valuation matters
The 409A in force on the grant date sets the strike, and the strike is what an exercise costs. Two people with the same number of options at the same company can face different costs because their grants fell on either side of a new valuation.
The 409A in force on the exercise date sets the spread, and the spread is what gets taxed. On an NSO it is ordinary income in the year of exercise. On an ISO it counts toward the alternative minimum tax.
Between funding rounds it is also the only outside estimate of what the shares are worth.
409A valuation in Taiga Finance
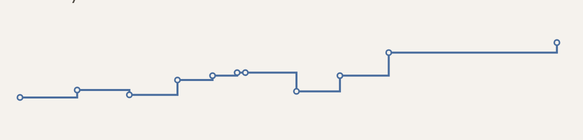
Taiga Finance draws each private company's 409A history as a stepped value-per-share line, with funding rounds marked on it. A new entry re-prices that company's grants, and a public company sits beside it on its market price.
Entries are typed in by hand or read from a Carta file. When an exercise is logged, its cost shows before it saves.
Equity compensation →Key takeaways: 409A valuation
- A 409A valuation is an outside appraisal of a private company's common stock, per share.
- It is presumed reasonable for up to 12 months, or until later information materially affects the value.
- The 409A on the grant date sets the strike. The 409A on the exercise date sets the taxable spread.
- It is a different figure from the price investors paid, because they bought preferred stock.
Questions about 409A valuation
How are private company stock options valued?
From the latest 409A. Vested options times the gap between the 409A and the strike gives the spread on paper. That figure is before tax, and a private company's shares may not be sellable, so it is an estimate and not cash.
Is a 409A valuation the same as the price investors paid?
No. Investors buy preferred stock, which has rights common stock lacks. The 409A values common stock, so it is a different figure from the last round's price.
How often does a 409A valuation change?
The tax regulations presume an appraisal reasonable for no more than 12 months, and for less when later information materially affects the value. It can go down as well as up.
Does Taiga Finance track a 409A history?
Yes. A private company keeps its own history, entered by hand or read from a Carta file, and Taiga Finance draws it as a value-per-share line.